Merck to acquire Silence Therapeutics for USD 1.3 billion
Germany’s Merck KGaA has agreed to acquire London-based Silence Therapeutics, adding a Phase III-ready siRNA therapy for the rare blood cancer polycythemia vera (PV) to its rare disease pipeline.
October 20, 2026


Merck will pay USD 20 in cash per American depositary share (ADS). That gives the deal an equity value of approximately USD 1.3 billion and an enterprise value of USD 1.1 billion. The offer is an 82% premium to Silence’s 30-day volume-weighted average share price as of October 16, 2026. The acquisition will be financed with new debt. It is expected to close in the first quarter of 2027, pending regulatory and shareholder approval.
At the center of the deal is divesiran, an injection given under the skin once every three months. PV is a chronic myeloproliferative neoplasm in which the body makes too many red blood cells, which can raise the risk of death from cardiovascular and thrombotic events. Divesiran silences TMPRSS6, a gene involved in regulating hepcidin, the body’s key regulator of iron metabolism. By raising hepcidin levels, the drug aims to limit the iron available for red blood cell production. This helps control hematocrit levels and reduces the need for frequent phlebotomies.
In the Phase II SANRECO study, 88% of patients treated with divesiran responded, compared with 19% on placebo. Over 36 weeks, the mean number of phlebotomies fell to 0.2 per patient on divesiran, versus 2.1 on placebo. The drug was well tolerated, with no new safety findings.
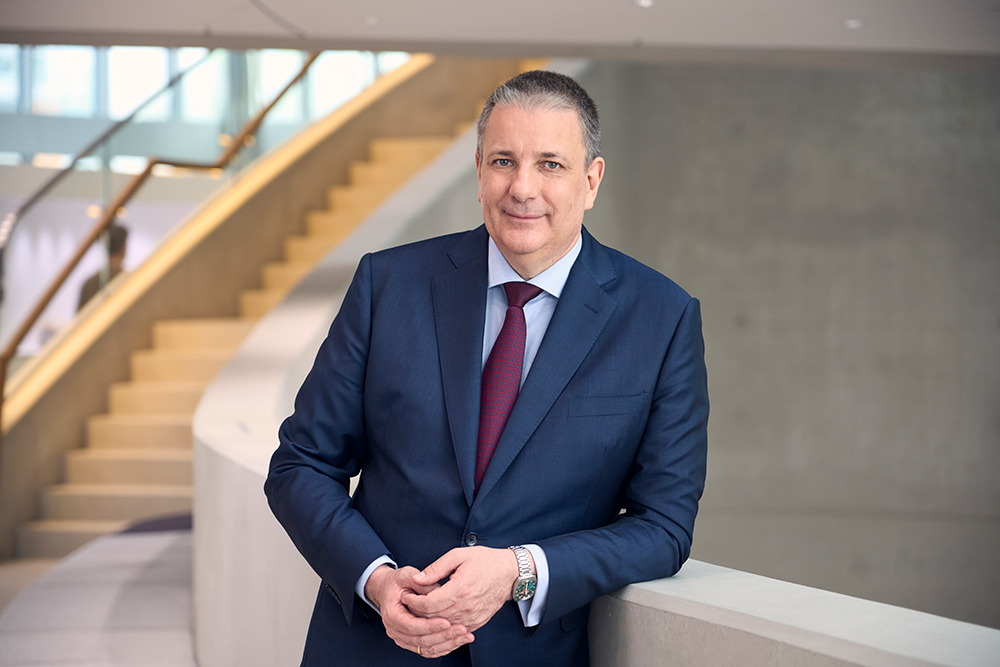
“The planned acquisition of Silence Therapeutics will strengthen our capabilities to serve patients with targeted specialty and rare diseases,” says Kai Beckmann, Chairman of the Executive Board and Group CEO, Merck. “Following the acquisition of SpringWorks Therapeutics last year, we continue to transform our pipeline toward areas of high specialization and unmet medical need.”
Danny Bar-Zohar, CEO Healthcare, Merck, adds that the deal also gives the company an entry point into hematology “through a biologically validated mechanism of action.”
Published: October 20, 2026